
Publication time reported by BabyLoveGrowth, shown in Mountain time. This is not an independently measured first appearance on this website.
Oct 15 to Dec 7, 2026: Medicare Open Enrollment Dates for Colorado
Fall Open Enrollment runs October 15 through December 7, 2026, and any plan change made in that window takes effect January 1, 2027. If you’re already in a Medicare Advantage plan, you get a second, narrower shot from January 1 through March 31 to make one correction. Plan details for the coming year usually post around October 1, so you have two weeks to look before Open Enrollment even starts.
SimplyinsuranceforyouGet Clear Medicare Enrollment GuidanceSimply Insurance provides personalized, independent guidance for comparing Medicare options and ongoing support with claims and annual reviews.Visit Simply InsuranceTL;DR:
- The Medicare Annual Enrollment Period runs from October 15 to December 7, 2026, with plan changes taking effect on January 1, 2027.
- Only current Medicare Advantage enrollees can switch plans during the Medicare Advantage Open Enrollment from January 1 to March 31, with most changes effective the first of the month after submission.
- Using the wrong enrollment window, such as confusing AEP with MA OEP, can lead to missing opportunities or making unnecessary errors.
- Preparing involves reviewing the detailed notice of change, comparing Medicare plans early, and submitting enrollment ahead of deadlines to avoid last-minute issues.
- Independent brokers can help clarify options and ensure timely, correct enrollment, often at no extra cost to beneficiaries.
Table of Contents
- When Is Medicare Open Enrollment 2026? Key Dates to Track
- Which Enrollment Period Applies to You?
- What Changes Can You Make During AEP?
- How Does the Medicare Advantage Open Enrollment Period Work?
- How to Prepare for Medicare Open Enrollment 2026
- A Local Broker’s View on Open Enrollment Help
- Get Help With Medicare Enrollment in Colorado
- Sources
- FAQ
When Is Medicare Open Enrollment 2026? Key Dates to Track
The Medicare calendar has a rhythm, and missing one beat throws off everything after it.
- October 1: Plans release next year’s costs, drug lists, and provider networks. This is when the Medicare Annual Notice of Change starts landing in mailboxes.
- October 15: The Medicare annual enrollment period officially opens. You can start comparing and switching plans the same day.
- December 7: Hard deadline. Your plan has to receive the enrollment request by this date for the change to count.
- January 1, 2027: Every AEP change, no exceptions, takes effect on this date.
- January 1 through March 31, 2027: The Medicare Advantage Open Enrollment Period, open only to people already in an MA plan.
Timing works differently inside MA OEP. A request submitted in January usually takes effect February 1; one submitted in March usually takes effect April 1. It’s the first of the month after the plan processes your request, not a fixed calendar date like AEP.
Which Enrollment Period Applies to You?
Two windows dominate the fall and winter calendar, and using the wrong one can waste months. Here’s how they break down:
- Annual Enrollment Period (Oct 15 to Dec 7): Open to anyone with Medicare. You can join, switch, or drop a Medicare Advantage plan, move between Original Medicare and MA, or join, switch, or drop a Part D drug plan.
- Medicare Advantage Open Enrollment Period (Jan 1 to Mar 31): Open only to people already enrolled in Medicare Advantage. You get one change: switch to a different MA plan, or drop MA and return to Original Medicare (adding Part D if needed).
- Initial Enrollment Period: The seven-month window around your 65th birthday, when you first sign up for Medicare.
- General Enrollment Period (Jan 1 to Mar 31): For people who missed their Initial Enrollment and need to sign up for Part A and/or Part B.
- Special Enrollment Periods: Triggered by specific events like moving out of a plan’s service area or losing employer coverage.
The confusion trips up a lot of people: MA OEP is not a second AEP. It’s a one-time correction window for current MA enrollees, and it doesn’t let you touch a standalone Part D plan unless you’re also leaving Medicare Advantage. Advocacy groups have flagged this exact mix-up as one of the more common enrollment errors each year.
What Changes Can You Make During AEP?
Fall Open Enrollment gives you the widest set of options all year. During this six-and-a-half-week window, you can:
- Switch from Original Medicare to a Medicare Advantage plan, or go the other direction.
- Move from one Medicare Advantage plan to another, even across carriers.
- Join a Part D drug plan for the first time if you have Original Medicare and skipped it before.
- Switch from one Part D plan to another.
- Drop Part D coverage entirely, though this can trigger a late enrollment penalty later.
- Add or drop drug coverage bundled with a Medicare Advantage plan.
Most of these decisions trace back to three things buried in the ANOC: a formulary that dropped your medication, a provider network that lost your doctor, or a premium and deductible that jumped for no obvious reason.
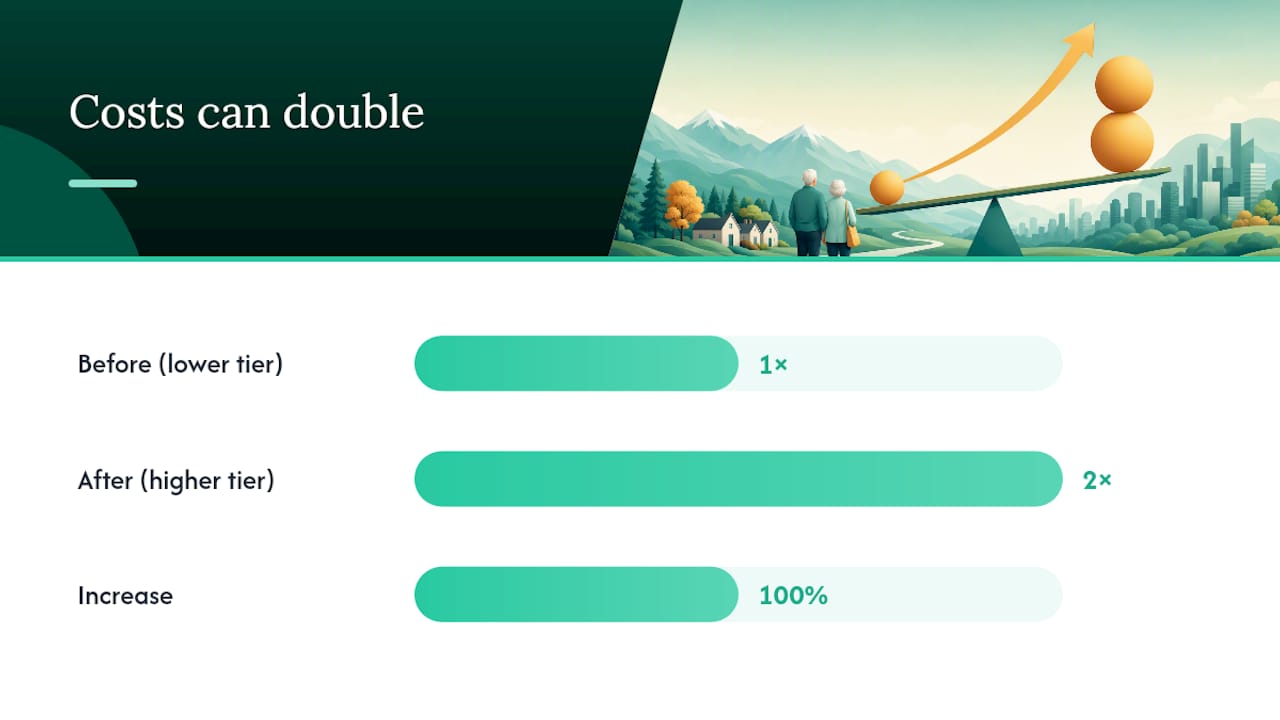
Pro Tip: Read your ANOC line by line before you decide anything. A plan that looks unchanged on the surface can quietly shift a specialty drug to a higher pricing tier, doubling what you pay out of pocket without ever sending a separate notice.
How Does the Medicare Advantage Open Enrollment Period Work?
MA OEP exists for one reason: to give current Medicare Advantage members a way to undo a bad AEP decision or fix a plan that isn’t working once real claims start coming in. It runs January 1 through March 31 every year, and it’s limited to people who were already enrolled in an MA plan on January 1.
- You get exactly one election during this window, not unlimited switching.
- You can move to a different Medicare Advantage plan, or drop MA and return to Original Medicare, adding a standalone Part D plan if you go that route.
- People in Medicare Medical Savings Account (MSA) plans, PACE programs, or certain cost plans don’t qualify for MA OEP.
- Changes typically take effect the first day of the month after the plan receives your request, so a February submission usually starts March 1.
It’s a safety net, not a strategy session. If you’re weighing several options carefully, AEP gives you far more room to compare before committing.
How to Prepare for Medicare Open Enrollment 2026
Getting ready for AEP is mostly about gathering the right information before the clock starts ticking.
- Starting October 1: Pull your ANOC, list every medication and dosage you take, and write down which doctors and specialists you see regularly.
- Compare your options: Use the Medicare Plan Finder to check costs, formularies, and networks side by side, or call 1-800-MEDICARE for unbiased help walking through the tool.
- Talk to a broker if you want a second set of eyes: An independent agent can flag network or formulary issues you might miss reading the ANOC alone.
- Submit early, not on December 6: Enroll online, by phone, through a broker, or with a paper plan form, then confirm the plan actually received it.
- Keep proof of submission: A screenshot, confirmation number, or email receipt protects you if there’s ever a dispute about timing.
The CMS partner resources page specifically warns beneficiaries to lean on Medicare.gov, the “Medicare & You” handbook, and 1-800-MEDICARE rather than unsolicited mail or calls, since marketing volume spikes hard every October. If your current Medicare Part D coverage still fits your medications and budget after that comparison, doing nothing is a legitimate choice. Just make that call after reading the ANOC, not before.
A Local Broker’s View on Open Enrollment Help
A licensed broker earns their keep translating the ANOC into plain terms, running side-by-side plan comparisons, and actually submitting the enrollment so nothing falls through on December 6. That last piece matters more than people expect. Annual reviews and claims support after enrollment catch problems an online tool never will, like a specialist visit that suddenly needs a referral.
Local knowledge counts for something too. A broker working Castle Pines and the greater Denver area knows which regional carrier networks actually cover the hospital systems and specialists people here use, not just which plan looks cheapest on paper.
— Zach
Get Help With Medicare Enrollment in Colorado
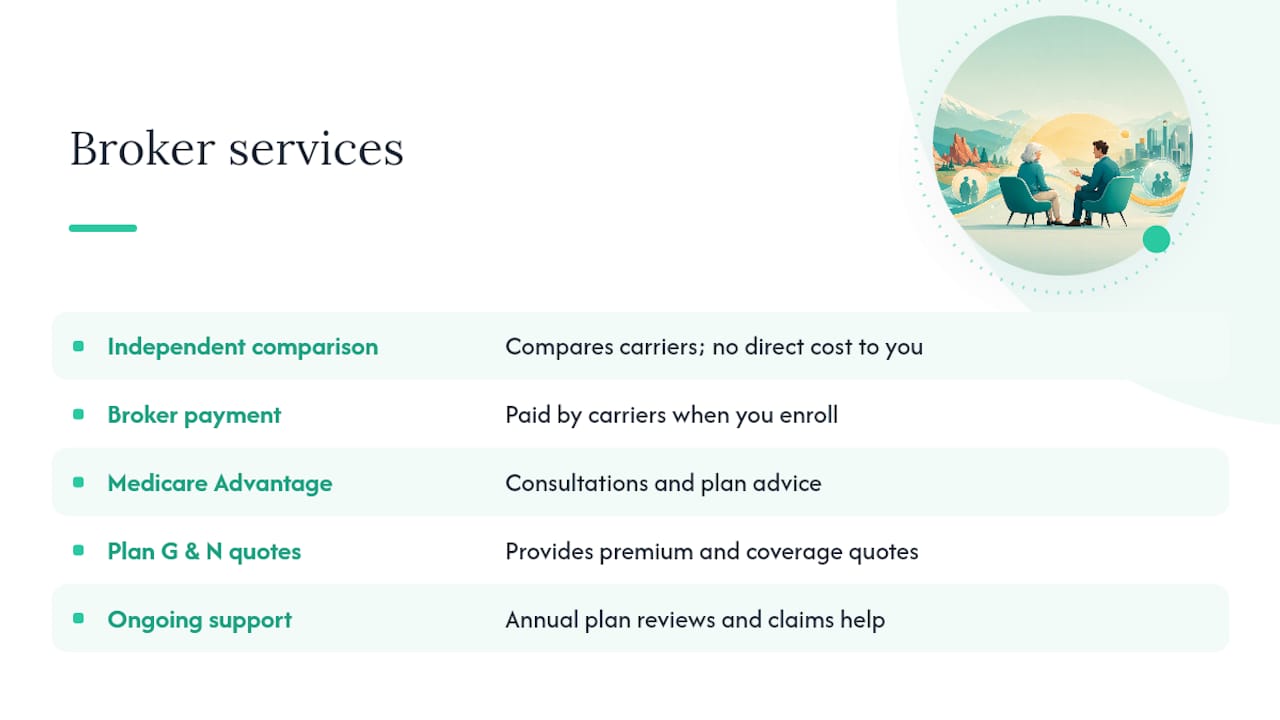
Some people prefer to use an independent broker to help sort through Medicare Advantage and Part D plans, with brokers comparing options across carriers instead of promoting a single company’s product. Guidance from an independent broker may come at no direct cost to you, as brokers typically receive payment from carriers when you enroll in a plan, keeping the advice free regardless of the plan chosen.

Beyond AEP, the team handles Medicare Advantage consultations, Plan G and Plan N quotes, and Social Security planning through RSSA®, plus help with appeals and grievances if a claim gets denied. Support may continue beyond enrollment, with annual plan reviews and claims assistance helping clients check their coverage regularly, not just the initial enrollment year.
If you’re in Castle Pines, Castle Rock, Centennial, or anywhere in Colorado and want a real person to walk through your options before December 7, start your Medicare planning with a licensed local broker today.
This article is general information, not a substitute for advice from a qualified doctor. Consult a qualified healthcare professional about your own circumstances before acting on anything here.
Sources
- Open Enrollment | Medicare
- Joining a plan | Medicare
- Medicare open enrollment partner resources | CMS
FAQ
What Won’t Medicare Cover in 2026?
Original Medicare generally doesn’t cover routine dental care, most vision exams and eyeglasses, hearing aids, long-term custodial care, and cosmetic procedures. Many Medicare Advantage plans add some of these benefits, which is one reason people compare plans during AEP rather than assuming coverage is identical everywhere.
Can I Drop Medicare Advantage and Go Back to Original Medicare?
Yes. You can make this switch during fall Open Enrollment (October 15 to December 7) or during the Medicare Advantage Open Enrollment Period from January 1 to March 31 if you’re already enrolled in an MA plan. Consider pairing the switch with a Part D plan and reviewing Medigap eligibility before you drop MA coverage.
Is Medicare Free at Age 65?
Part A is usually premium-free if you or a spouse paid Medicare taxes for enough quarters of work, but Part B carries a monthly premium regardless of work history. Medicare Advantage and Part D plans have their own separate premiums, deductibles, and copays that vary by plan.
Can You Enroll in Medicare Anytime During the Year?
No. Enrollment is tied to specific windows: your Initial Enrollment Period around turning 65, the fall Annual Enrollment Period from October 15 to December 7, the General Enrollment Period from January 1 to March 31, and qualifying Special Enrollment Periods triggered by events like a move or job loss. Missing your window can mean a wait of months and a late enrollment penalty on Part B or Part D.
Do I Need a Broker to Enroll in Medicare?
No, you can enroll directly through Medicare.gov or by calling 1-800-MEDICARE. Many people choose a licensed independent broker like Simply Insurance instead, since comparing carrier networks and formularies across multiple companies without help can take hours that a broker’s plan comparison shortens considerably.